
TS Pulse: Hawks push UK rate expectations higher
The Bank of England’s expected hike to 4% came with a more hawkish tone than the market anticipated, but we think weaker growth could see rates peak well below the 5% currently priced in.
A 25bps hike in the UK bank rate to 4% had been fully expected by the market. However, the hawkish nature of MPC members’ comments seemingly caught some by surprise, pushing short-term rates higher
Following last month’s 6-3 vote in favour of holding rates, an 8-1 split in favour of a hike this month didn’t surprise us… until we realised the one had voted for a 50bps hike.
As the members’ comments were published, the tone read to us as more urgent than at previous meetings and the market reacted similarly, pushing short-term rates 6-7bps higher and bringing December into play for a hike, from just a 20% likelihood ahead of this meeting.
Catherine Mann voted for a 50bps hike, saying it would have been “good policy”, Governor Bailey said that “a further increase in the Bank Rate may be likely”, while four others suggested another hike is probable at one of the next two meetings.
However, Bailey also said “today’s increase shouldn’t be seen as the first in an inevitable long sequence of hikes”, and the Bank’s central scenario sees inflation dropping to the 2% target in two years, with forecasts for GDP growth revised up to 1.6% from 1.1% in 2026 and to 1.4% from 1.0% in 2027.
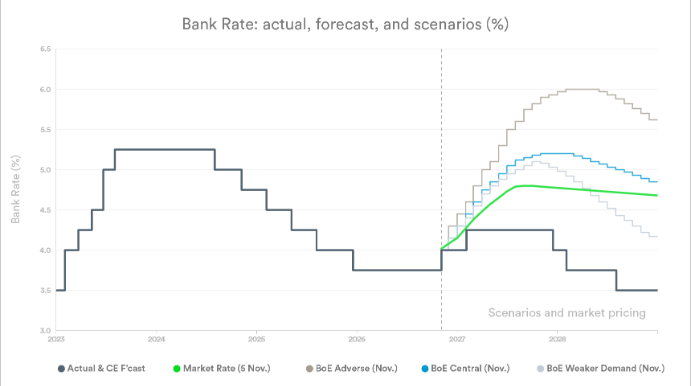
In our opinion, the risk is that GDP growth underperforms, meaning inflation falls back to target sooner, and rates don’t reach anywhere near the 5% peak the market is implying.
Energy prices obviously still have a hand to play in this, and will be subject to events in the Gulf, but the oil price falls in the last few days will be helping cap the upside to inflation.
Below is a chart, courtesy of Capital Economics, using data from them, LSEG Data, and the Bank of England, showing the Bank’s inflation scenarios through 2028, the market-implied rates, and CE’s forecast. Our thoughts are more aligned with CE’s forecast.
*TreasurySpring’s blogs and commentaries are provided for general information purposes only, and do not constitute legal, investment or other advice.

Subscribe to Insights
Explore flexible, diversified funding, built around your requirements.


